Earnings momentum to macroeconomic validation

RECAPPING LAST WEEK


After dipping early in the week, pressured by rising yields and the imminent possibility of renewed
military conflict with Iran, US equity indices reversed course by midweek and ended up either just
beneath (S&P 500), at (Nasdaq 100), or above all time highs (DJIA.) Nvidia, the bluest of the blue–
chip chipmakers, announced earnings and revenues that once again beat street estimates, yet the
stock and broader market barely responded. Increased spending by U.S. hyperscalers more than
made up for CEO Jensen Huang conceding the Chinese AI chip market, their market share having
fallen from 90% to zero. Thursday the U.S announced that it would be investing $2B in quantum
computing–related stocks. A billion of that is going to IBM, which is up over 15% since the
announcement, and the smaller pure–play quantum stocks that will be receiving the remaining
funds (Global Foundries–GFS, D–Wave Quantum–QBTS, Rigetti Computing–RGTI, and Infleqtion–
INFQ) rallied as much as 50% on the news. S&P500 sector performance reflected a broadening
but defensive–leaning rally, with utilities and health care seeing the largest gains for the week,
followed by real estate, while technology remained supported by AI and semiconductors. U.S.
Treasuries were the key macro pressure point, with 10–year Treasury yields reaching their highest
levels since January 2025 and the 30–year touching their highest level since 2007. Inflation worries,
energy–price risk, and a less–dovish Fed path weighed on duration, yet by end of week, yields had
returned to last week’s closing levels. Fed funds futures now indicate a mere 32% probability of
rates remaining where they are at year end, a 42% probability of a quarter point hike, with chances
for rates being 50 or 75 basis points higher comprising the remaining possibilities. After moving
decisively higher against most major currencies the prior week, the U.S. dollar consolidated in a
fairly tight range. Even a report showing Japanese core inflation running at 4–year lows wasn’t
sufficient to push USD/JPY out of the 159 range where it meandered all week. Crude oil spent the
week gyrating around $100 before peaking north of $105 ahead of President Trump calling off a
planned Tuesday attack against Iran, citing his optimism over ongoing “serious negotiations.” The
July contract settled near two–week lows at $96.60. Precious metal and crypto markets rounded
out the theme of a quiet pre–holiday week whereby in the absence of catalysts, consolidation ruled
the week.


THE WEEK AHEAD


The last week of May sees a holiday shortened week, with not only U.S. markets closed Monday for
Memorial Day but UK markets (Spring Bank Holiday) and continental European markets (Whit
Monday) as well. Attention will likely shift from earnings momentum to macroeconomic validation,
with markets watching the equity rally for challenges posed by elevated yields and oil–linked
inflation. The global economic calendar remains pretty light, with inflation related economic
releases attracting the most attention. Australian CPI is released Tuesday, with expectations of a
hot year–over–year reading of 4.4%. Thursday sees the release of the U.S. Personal Consumption
Expenditures index–any mention of which one is seemingly obligated to state “the Fed’s preferred
inflation gauge.” A distinct way in which the PCE differs from CPI is that it accounts for consumer
substitution of goods rather than using a fixed basket of goods. Hence, when inflation is rising, as
is now, driven by energy prices, consumers adjusting their spending by “trading down” in other
areas is something that PCE can capture that CPI does not. So, expectations are for the core PCE
numbers to come in at a relatively benign 0.3% month over month and 3.5% year over year. New
home sales, which arrive Thursday, will provide a key rate–sensitivity check for the sector. A
handful of tech companies report on Wednesday; Marvell Technologies (MRVL), Salesforce (CRM),
Snowflake (SNOW), Synopsis (SNPS), and HP (HPQ), with Dell (DELL) rounding out earnings
season on Thursday along with retail giant Costco (COST.)

(Schwab)

Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

Short-term yields rising

Global equity markets remained remarkably resilient last week despite another sharp rise in interest rates, elevated energy prices, and the first rate hike from the Federal Reserve in more than three years. U.S. equities initially came under pressure following Wednesdays widely anticipated 25 basis point increase in the Fed Funds target rate to 3.75%-4%, but the selloff was relatively short-lived, with most major indices recovering from their knee-jerk response to the rate announcement.

Read more →

Investors focused on the FOMC’s 2-day meeting

Global equity markets were under pressure last week with rising energy prices, escalating U.S.-Iran hostilities, and another leg higher in Treasury yields. U.S. equities gave back much of the gains from the prior week, with the S&P 500, Nasdaq 100, and Russell 2000 all slipping a little Tuesday through Thursday before regaining some ground on Friday. The selloff was relatively orderly, with the market continuing to focus on whether the increase in energy prices represents a temporary
geopolitical shock or the beginning of a more persistent inflation problem.

Read more →

Final look at inflation data

Global equity markets were quietly choppy this week as investors grappled with a rise in global bond yields, a renewed escalation in U.S.-Iranian hostilities and a shifting outlook for Fed policy.U.S. equities came under pressure early in the week as the global bond selloff and higher energy prices challenged elevated valuations, although stocks recovered as the week progressed, with theS&P 500, Nasdaq 100, and Russell 2000 posting modest gains of under a half a percent.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

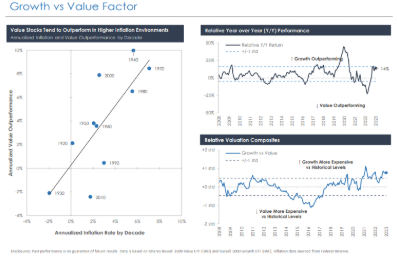
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.