Research library

Market Research

Every report across our four research series — weekly, monthly, quarterly and global.

Packed economic and earnings calendar

U.S. equities delivered a mixed performance this week as investors navigated a sharp decline in Treasury yields, escalating geopolitical risk, and growing concerns about the sustainability of the
AI investment boom. Beneath the headline indices, the divergence between technology stocks and the broader market became increasingly pronounced as investors reassessed the valuations of companies at the center of the AI trade.
Read more →

Hotter-than-expected inflation data pressures markets

U.S. equities came under renewed pressure this week as hotter-than-expected inflation data forced investors to reassess both the interest rate outlook and the sustainability of the AI investment boom. The September CPI report showed headline inflation rising 0.6% for the month and 3.7% year-over-year, while core CPI increased 0.3% for the month and 2.6% for the year—this reading comes in above both the Fed’s stated 2.0% target and the high end of economist expectations.

Read more →

Credit-market stability and earnings quality

U.S. equity markets overall continued to rise, with both the S&P 500 and Nasdaq notching fresh all-time highs. The beleaguered Russell small cap index, however, continued to underperform. European markets were down modestly while Asian markets advanced. Treasury yields surged to fresh highs on Wednesday before cooling by the week’s end as rates and borrowing costs remained a major focus.

Read more →

Bond markets under pressure

Global equity markets remained resilient last week despite another sharp rise in Treasury yields, with the 10-year yield surging to 5.34%, its highest level since 2002, before pulling back following Friday’s benign employment report. The rise in yields reflected persistent inflation concerns, elevated energy costs and increasing expectations that interest rates will remain higher for longer.

Read more →

The Fed’s preferred inflation gauge

Global equity markets remained remarkably resilient last week despite a sharp rise in interest rates, with the 10-year firmly pushing through 5% with yields on maturities as short as the 3-year now at that level. Expectations are now firmly entrenched that the recent Fed hike was anything but a “one and done” as Fed Funds futures pricing now reflects a peak rate of 4.75-5% by mid-summer, fully 100 basis points higher than the current band.

Read more →

Short-term yields rising

Global equity markets remained remarkably resilient last week despite another sharp rise in interest rates, elevated energy prices, and the first rate hike from the Federal Reserve in more than three years. U.S. equities initially came under pressure following Wednesdays widely anticipated 25 basis point increase in the Fed Funds target rate to 3.75%-4%, but the selloff was relatively short-lived, with most major indices recovering from their knee-jerk response to the rate announcement.

Read more →

Investors focused on the FOMC’s 2-day meeting

Global equity markets were under pressure last week with rising energy prices, escalating U.S.-Iran hostilities, and another leg higher in Treasury yields. U.S. equities gave back much of the gains from the prior week, with the S&P 500, Nasdaq 100, and Russell 2000 all slipping a little Tuesday through Thursday before regaining some ground on Friday. The selloff was relatively orderly, with the market continuing to focus on whether the increase in energy prices represents a temporary
geopolitical shock or the beginning of a more persistent inflation problem.

Read more →

Final look at inflation data

Global equity markets were quietly choppy this week as investors grappled with a rise in global bond yields, a renewed escalation in U.S.-Iranian hostilities and a shifting outlook for Fed policy.U.S. equities came under pressure early in the week as the global bond selloff and higher energy prices challenged elevated valuations, although stocks recovered as the week progressed, with theS&P 500, Nasdaq 100, and Russell 2000 posting modest gains of under a half a percent.

Read more →

Payrolls are expected to recover

Global markets were relatively quiet this past week with most major macro asset classes modestly reversing some of the prior week’s sharper moves in a quiet consolidation. The S&P 500 and Nasdaq 100 each rose about a half of a percent, while the small-cap Russell 2000 fell 1.5%.

Read more →

July FOMC minutes in focus

Equity markets continued their march higher last week, as the S&P500 and Russell 2000 hit new all-time highs for the second consecutive week. The NASDAQ came within 2% of its early June all-time high, though it continues lagging its counterparts.

Read more →

This Week Could Reset the Market Narrati

The dominant theme in global equity markets this past week was the intersection of earnings season, monetary policy and the ongoing repricing of the semiconductor sector. With more than one-third of the S&P 500 reporting quarterly results, for the most part corporate America continued delivering resilient earnings growth despite a backdrop of higher interest rates and persistent inflation.

Read more →

No Summer Doldrums

The dominant theme in U.S. equity markets last week was the sharp repricing of hyperscalers, prompted by investors showing little tolerance for rising capital expenditures tied to AI infrastructure.

Read more →

Get every new report as it’s published

Monthly Market Beat, Quarterly Perspective and Global Equity Analysis — delivered to your inbox.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

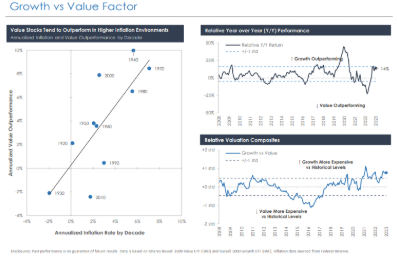
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.