Non-farm payrolls report is the week’s marquee event

RECAPPING LAST WEEK

U.S. equities extended their rally for a ninth consecutive week, with the S&P 500 climbing as easing oil prices,
resilient earnings, and AI-linked momentum overcame inflation concerns. Alongside the S&P, the Nasdaq-100,
Nasdaq Composite, and DJIA all closed at record highs on Friday, with only the Russell 2000 pulling back a
touch from Thursday’s record close. Dell’s (DELL) earnings blowout announcement was just the latest example
in a growing list of companies benefiting by massive AI infrastructure spending in a week that also saw Micron
(MU) join the trillion-dollar market cap club. S&P 500 sector performance favored growth and technology,
while consumer discretionary responded well to the lessening of inflation expectations amid a sharp drop in
energy prices which in turn lessened the likelihood of rate hikes. Of course, the flip side of the sector
performance coin was energy as the worst performer followed by consumer staples. U.S. Treasury yields
eased throughout the week, improving risk sentiment, though the broader rate backdrop remains fragile. The
10- year settled below 4.5% and the 30-year under 5%, while the 2-year note, more sensitive to short-term
rate expectations, remained above 4%. Overall, foreign currency markets were quiet amid the minor shifting of
interest rate expectations. For the Yen, this quietness masked a great deal of activity beneath the surface:
over the past month the Japanese Ministry of Finance intervened in the currency markets for the first time
since 2024 selling over $73 billion USD/JPY to support the Yen. As a mercantilist, export-driven economy,
Japan would normally welcome a weaker currency, but in this case concerns about the nation’s dependence
on dollar-denominated imported energy seems to have been the overriding concern. In spite of ongoing
small-scale military skirmishes, progress on the U.S./Iran diplomatic front led to a nearly $10 per barrel
decline in the price of oil. U.S. priorities seem to be getting the Strait of Hormuz open even while Iran, through
its public statements, isn’t backing down from what they claim is their right to enrich uranium. For now, the
market seems focused on the prospect for oil to be able to make it’s way out of the Persian Gulf again.
Precious metals were quiet, apparently neither a risk-on nor risk-off proxy this week, while over the past two
weeks, the insatiable demand for tech stocks has led to a negative correlation of crypto with equities.
0–

year settled below 4.5% and the 30–year under 5%, while the 2–year note, more sensitive to short–termiable demand for tech stocks has led to a negative correlation of crypto with equities.THE WEEK AHEAD

The June 5 U.S. non–farm payrolls report is the week’s marquee event, with markets eager to learn
whether labor will put up strong numbers, meaning the Fed will be likely to leave rates higher for
longer, or will show signs of cooling, which could ease Treasury yield pressure. Macro investors will
also be watching developments in U.S.–Iranian negotiations—If the market sees continued
momentum toward a solution that reopens the Strait of Hormuz, lower energy prices and inflation
expectations could be on the horizon. This would extend the virtuous circle whereby these trends
reduce the chance of rate hikes, which in turn could support the ongoing sharp rally in equity
markets. Of course, if talks fail and and the U.S. revives its active military campaign, equity markets
could very well be facing the same headwinds of higher inflation expectations due to a sustained
increase in energy prices which they’ve previously pushed through. ISM manufacturing and services
data will help clarify the growth/inflation mix, clarifying whether companies’ efforts to pass higher
input costs through to consumers are resulting in softening demand. If energy prices remain under
pressure, the market’s focus on inflation numbers will likely shift toward growth and employment
data, the latter of which we’ll see plenty of this week. In addition to Friday’s report, Tuesday sees the
JOLTS job openings number, Wednesday brings data from the private payroll company ADP, and the
weekly jobless claims numbers arrive on Thursday.

(Schwab)

Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

Short-term yields rising

Global equity markets remained remarkably resilient last week despite another sharp rise in interest rates, elevated energy prices, and the first rate hike from the Federal Reserve in more than three years. U.S. equities initially came under pressure following Wednesdays widely anticipated 25 basis point increase in the Fed Funds target rate to 3.75%-4%, but the selloff was relatively short-lived, with most major indices recovering from their knee-jerk response to the rate announcement.

Read more →

Investors focused on the FOMC’s 2-day meeting

Global equity markets were under pressure last week with rising energy prices, escalating U.S.-Iran hostilities, and another leg higher in Treasury yields. U.S. equities gave back much of the gains from the prior week, with the S&P 500, Nasdaq 100, and Russell 2000 all slipping a little Tuesday through Thursday before regaining some ground on Friday. The selloff was relatively orderly, with the market continuing to focus on whether the increase in energy prices represents a temporary
geopolitical shock or the beginning of a more persistent inflation problem.

Read more →

Final look at inflation data

Global equity markets were quietly choppy this week as investors grappled with a rise in global bond yields, a renewed escalation in U.S.-Iranian hostilities and a shifting outlook for Fed policy.U.S. equities came under pressure early in the week as the global bond selloff and higher energy prices challenged elevated valuations, although stocks recovered as the week progressed, with theS&P 500, Nasdaq 100, and Russell 2000 posting modest gains of under a half a percent.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

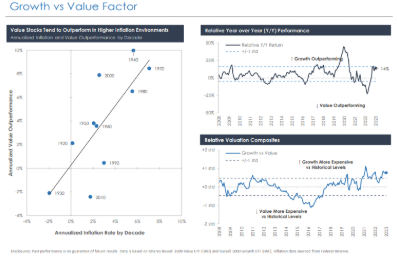
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.