Big Earnings on Deck

RECAPPING LAST WEEK

U.S. equity indices managed to hold onto weekly gains despite macroeconomic headwinds,
including the ongoing government shutdown, trade tensions with China, and rising concerns
about private credit and regional bank loans. The S&P500 and Nasdaq Composite indices gained
around 2%, while the Russell 2000 ended higher by 2.4%, declining slightly from a new record
high reached midweek. All sectors posted positive performance, but financials lagged despite
strong earnings reports from the large U.S. banks. Shares of Zions Bancorp tumbled after
revealing losses tied to commercial and industrial loans, while Western Alliance sank after
disclosing a lawsuit it had initiated regarding a business loan. Gold futures jumped over 7% to
near $4,400 before pulling back on Friday after some positive signs emerged in U.S.–China trade
relations. President Trump said that the proposed 100% tariffs on goods from China were not
sustainable and confirmed that he would meet with Chinese President Xi Jinping in two weeks. Oil
futures fell 1.7% while cryptocurrency prices remained under pressure for a second straight week.
U.S. economic news was limited as the government shutdown extended into a third week, with no
resolution in sight. As a result, Treasury yields briefly touched the lowest level since April as
investors remained somewhat in the dark on the health of the U.S. economy. At a conference, Fed
Chair Powell delivered prepared remarks noting that data available prior to the shutdown reflected
economic activity on a modestly firmer trajectory than expected. He also said the outlook for
inflation and employment does not appear to have changed since the last FOMC meeting,
signaling that another quarter–point rate cut is likely later this month. With September’s official
retail sales report delayed, the Chicago Fed Advanced Retail Trade Summary estimated a 0.5%
advance, though higher prices likely impacted that rise. Regional manufacturing surveys showed
mixed results, as activity increased modestly in New York state this month while the Philadelphia
area slumped to the lowest level since April. The release of housing starts and permits was
delayed, but the latest NAHB housing index reading jumped to 37 in October from 32 as future
sales expectations topped the breakeven level of 50 on optimism for lower mortgage rates.
Overseas, China’s exports rose 8.3% last month while shipments to non–U.S. ports grew nearly
15%. The limited impact from U.S. tariffs on overall trade may give China leverage in trade
negotiations. Domestic consumption remained weak as China’s consumer and producer prices
fell 0.3% and 2.3% YoY, respectively. Finally, the British economy expanded by just 0.1% in
August, suggesting that Q3 GDP may decelerate from the lackluster 0.3% growth in Q2. UK
employment has held up better than expected, however, and wage growth has cooled slightly.

THE WEEK AHEAD

Although the S&P500 and Nasdaq Composite indices clawed back roughly half of the prior week’s
losses, and the Russell 2000 reached a new high, the volatility index’s elevated level suggests
that investors remain on edge. Late last week VIX nearly touched 29 in the Thursday–into–Friday
overnight session before settling close to 21—still indicating a healthy amount of fear given lofty
equity values. This week, investors hope for progress on ending the shutdown and more clarity on
trade issues, while keeping an eye on geopolitical events and the credit markets. In the U.S., the
delayed September CPI report is scheduled for Friday—observers expect headline inflation to
have increased 0.4% MoM and 3.1% YoY—an increase from 2.9% YoY the prior month. The other
important economic releases will be the flash PMI surveys for the manufacturing and services
sectors along with revised consumer sentiment and inflation expectations. Several earnings
announcements have market–moving potential, with reports due from Netflix, Tesla, IBM, Texas
Instruments, and Intel, among others. On the international agenda, China may set the early tone
for the week with the release of GDP, industrial production, and retail sales figures on Sunday
evening. In Japan, all eyes will be on the political process for election of the new prime minister,
set for Tuesday, while the latest inflation update arrives Thursday. Finally, in Europe the focus will
be on the flash PMI readings, plus UK CPI and retail sales.


(Schwab)

Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

NVDA CEO out….or back in?

U.S equities staged a sharp rebound, recovering much of the prior week’s selloff despite continued weakness in one of the market’s largest components, Nvidia. The S&P 500 and Nasdaq advanced strongly as investors looked beyond the turmoil in the AI trade and responded to improving corporate earnings. The rebound was…

Read more →

Rebounding after a turbulent week

U.S. equities endured a turbulent week: after markets initially welcomed decisive victories that would leave no room for protracted court battles contesting the midterm results, investors on Thursday reassessed the implications for the massive AI infrastructure buildout in the wake of a number of states’ and municipalities’ anticipated opposition to data center construction.

Read more →

U.S. congressional elections to command attention this week

Technology and energy markets diverged sharply this week, while the Federal Reserve’s steady hand proved less decisive than initially suggested. Equities opened on a constructive note Monday following news of Anthropic’s S-1 filing, but sentiment reversed by midweek as hyperscaler earnings from Alphabet, Amazon, and Intel reignited concerns over the scale of AI-related capital expenditure.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

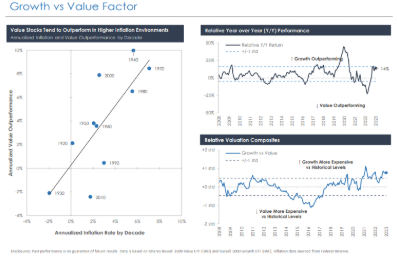
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.