Hotter-than-expected inflation data pressures markets

RECAPPING LAST WEEK


U.S.
equities came under renewed pressure this week as hotter–than–expected inflation data
forced investors to reassess both the interest rate outlook and the sustainability of the AI
investment boom. The September CPI report showed headline inflation rising 0.6% for the month
and 3.7% year–over–year, while core CPI increased 0.3% for the month and 2.6% for the year—this
reading comes in above both the Fed’s stated 2.0% target and the high end of economist
expectations. Thursday’s PPI report was even more concerning, with producer prices rising 6.3%
year–over–year versus expectations of 5.4%. The reports initially pushed Treasury yields higher and
weighed heavily on technology stocks, with the Nasdaq suffering its largest one–day decline since
July. The week’s tech selloff may have begun due to concerns about higher interest rates but
continued due to renewed concerns over the enormous amount of debt being used to finance the AI
infrastructure buildout. CoreWeave became the focal point of those concerns, with its shares falling
sharply, the yield on its unsecured 5–year corporate bond rising to over 15% and the 5–year credit
default swaps (the cost to insure that debt) rising to over 11%. These concerns spilled over into the
broader AI complex, particularly impacting companies dependent on continued access to cheap
capital to fund aggressive expansion. The deterioration in equities ultimately produced a flight–to–
quality move into Treasuries, driving 10–year yields down toward 5%. The bond rally helped stabilize
equities on Thursday as investors took comfort in the reversal of yields that had been pushing
steadily higher. However, the selloff in equities resumed on Friday and coincided with an intraday
spike in the VIX above 22 before closing just beneath 20. The increase in the market’s “fear gauge,”
reflected via option pricing, is anticipating additional volatility in the coming days. Energy markets
rallied as geopolitical risks intensified. A container ship and a dry bulk carrier were sunk as Iran
cast doubt on US claims to be in sole control of that contested waterway. Combined with Houthi
attacks on Saudi energy infrastructure, this escalation kept crude oil prices firm throughout the
week. Refining margins for diesel remained near the post–Iranian conflict record levels we’ve
highlighted over the past several weeks. The International Energy Agency warned this week that it
expects the global diesel market to remain extremely tight well into 2027, primarily due to loss of
refining capacity in the Middle East and Russia. In other macro sectors, the Dollar rallied further into
one–year highs off the back of the hotter–than–expected CPI report before reversing course late in
the week as Treasury yields declined. The response from gold and crypto was precisely the
opposite, though far more muted—they were each pressured a bit in the immediate aftermath of the
CPI report then regained their footing with the Treasury rally. Late–week reversals only took a little
pressure off emerging markets as South Korea and Taiwan were affected much more by the
AI/semiconductor trade than by macro currency and interest rate influences.


THE WEEK AHEAD


The coming week will offer investors another opportunity to assess the resilience of the
U.S.
economy as markets continue to balance persistent inflation pressures against growing concerns
about the outlook for growth. Housing will be a particular focus, with the NAHB Housing Market
Index releasing Monday, followed by September building permits and housing starts on Tuesday.
With 30–year mortgage rates recently climbing to 7.4%, the housing sector faces renewed
affordability pressures at a time when elevated home prices are already weighing on demand.
Beyond housing, investors will remain focused on the fallout from the recent selloff in the
semiconductor sector and the weaker hands in the AI infrastructure buildout space. The resulting
flight to quality bid in Treasuries that lowered yields on the longer end of the curve will bear close
scrutiny—can these levels be maintained or were they a temporary knee–jerk response to AI debt
concerns. If investors feel confident that we’ve already seen the high point in yields, that could
provide the fuel needed to push the markets higher. Even with all the headline grabbing news in
the AI sector, the S&P 500 remains only a few percent off its all–time high

(Schwab)

Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

Credit-market stability and earnings quality

U.S. equity markets overall continued to rise, with both the S&P 500 and Nasdaq notching fresh all-time highs. The beleaguered Russell small cap index, however, continued to underperform. European markets were down modestly while Asian markets advanced. Treasury yields surged to fresh highs on Wednesday before cooling by the week’s end as rates and borrowing costs remained a major focus.

Read more →

Bond markets under pressure

Global equity markets remained resilient last week despite another sharp rise in Treasury yields, with the 10-year yield surging to 5.34%, its highest level since 2002, before pulling back following Friday’s benign employment report. The rise in yields reflected persistent inflation concerns, elevated energy costs and increasing expectations that interest rates will remain higher for longer.

Read more →

The Fed’s preferred inflation gauge

Global equity markets remained remarkably resilient last week despite a sharp rise in interest rates, with the 10-year firmly pushing through 5% with yields on maturities as short as the 3-year now at that level. Expectations are now firmly entrenched that the recent Fed hike was anything but a “one and done” as Fed Funds futures pricing now reflects a peak rate of 4.75-5% by mid-summer, fully 100 basis points higher than the current band.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

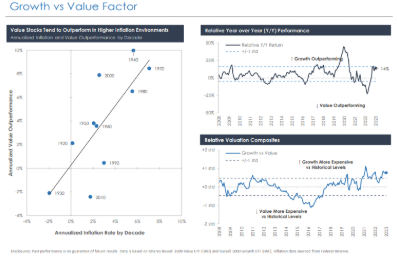
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.