Fundamental regime change” underway

May 28th, 2025

RECAPPING LAST WEEK

Volatility returned as rising interest rates and fresh tariff threats sent U.S. equity indices lower for the week. The S&P500 and Nasdaq Composite index each slumped 2.5%, while the Russell 2000 tumbled 3.5%. International equities fared better, with the MSCI EAFE index posting a 1.3% gain. All S&P500 sectors finished in the red, with technology sliding 3.4% after the White House targeted Apple with a 25% tariff for iPhones sold but not manufactured in the U.S. The energy sector plunged 4% as crude oil prices remained under pressure from looming production increases. Gold futures jumped 5%, boosted by a sinking U.S. dollar and a new wrinkle in the trade wars—a proposed 50% levy on European Union goods. Bitcoin soared to a new record high near $112,000 before pulling back to end the week with a 5% gain. The continued selloff in longer-dated U.S. Treasury bonds pushed yields up—the 30-year rate reached 5.15%, its highest level since 2007. A weak 20-year auction and concerns over rising budget deficits were contributing factors. Turning to economic data, U.S. business activity improved this month, although price pressures persisted. The S&P Global flash PMI composite index edged up to 52.1, lifted by a surge in new manufacturing orders. Sales of new U.S. homes rose 10.9% in April, spurred by lower
prices and higher incentives for buyers. The increase in the median price of existing homes saw the slowest appreciation in nearly two years. In corporate earnings news, Home Depot missed profit expectations but stuck to its previous guidance numbers, while Target slashed its forecast after posting a sharp decline in same-store sales. Overseas, China’s industrial production increased more than expected last month, though weaker retail sales reflected continued domestic consumption challenges. China’s central bank reduced its benchmark lending rates for the first time since October as policymakers sought to buffer the economic impact from trade conflicts. The Reserve Bank of Australia cut rates by 25 basis points to 3.85%, and investors anticipate two additional cuts later this year. Japan’s core CPI jumped the most in two years, rising to 3.5% YoY in April and supporting a Bank of Japan rate hike in July. The UK also suffered a larger-than-expected inflation spike last month, potentially further slowing the country’s already gradual rate-cutting pace. Canada’s annual inflation rate fell to 1.7% as energy prices dropped, but core measures remained higher. Finally, the European Central Bank, in its Financial Stability
Review, said a “fundamental regime change” could be underway, with investors reassessing the risk of U.S. assets. Business PMI surveys from the Eurozone showed a drop in services activity, previously the bloc’s main economic growth driver.

THE WEEK AHEAD

A shortened week awaits as U.S. markets were closed on Monday for the Memorial Day holiday. Investors will return from the three-day weekend wary of any fallout from last week’s tariff announcements and several important economic releases coming this week. In the U.S., minutes from the recent FOMC meeting come out Wednesday, followed by the second estimate of Q1 GDP on Thursday. April’s core PCE price index arrives Friday, though little change is expected, as any inflationary impact from tariffs will take time to feed into the calculation. Technology bellwether Nvidia will report earnings Wednesday after the market closes. Other releases on the domestic economic calendar include durable goods orders, trade balance figures, pending home sales, and May’s revised consumer sentiment reading, along with inflation expectations. On the international side, inflation updates are on the agenda in Australia, Japan, and Germany. Last of all, China’s manufacturing and services PMIs will be released Friday evening.

Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

Rebounding after a turbulent week

U.S. equities endured a turbulent week: after markets initially welcomed decisive victories that would leave no room for protracted court battles contesting the midterm results, investors on Thursday reassessed the implications for the massive AI infrastructure buildout in the wake of a number of states’ and municipalities’ anticipated opposition to data center construction.

Read more →

U.S. congressional elections to command attention this week

Technology and energy markets diverged sharply this week, while the Federal Reserve’s steady hand proved less decisive than initially suggested. Equities opened on a constructive note Monday following news of Anthropic’s S-1 filing, but sentiment reversed by midweek as hyperscaler earnings from Alphabet, Amazon, and Intel reignited concerns over the scale of AI-related capital expenditure.

Read more →

Packed economic and earnings calendar

U.S. equities delivered a mixed performance this week as investors navigated a sharp decline in Treasury yields, escalating geopolitical risk, and growing concerns about the sustainability of the
AI investment boom. Beneath the headline indices, the divergence between technology stocks and the broader market became increasingly pronounced as investors reassessed the valuations of companies at the center of the AI trade.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

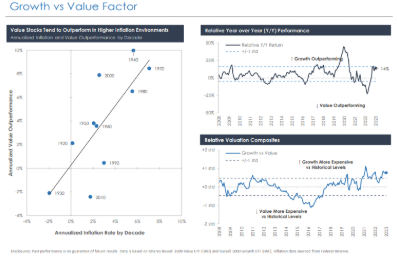
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.