Stocks Trade Higher in February as the Rally Broadens Out

Monthly Client Update | March 1, 2024

Monthly Market Summary

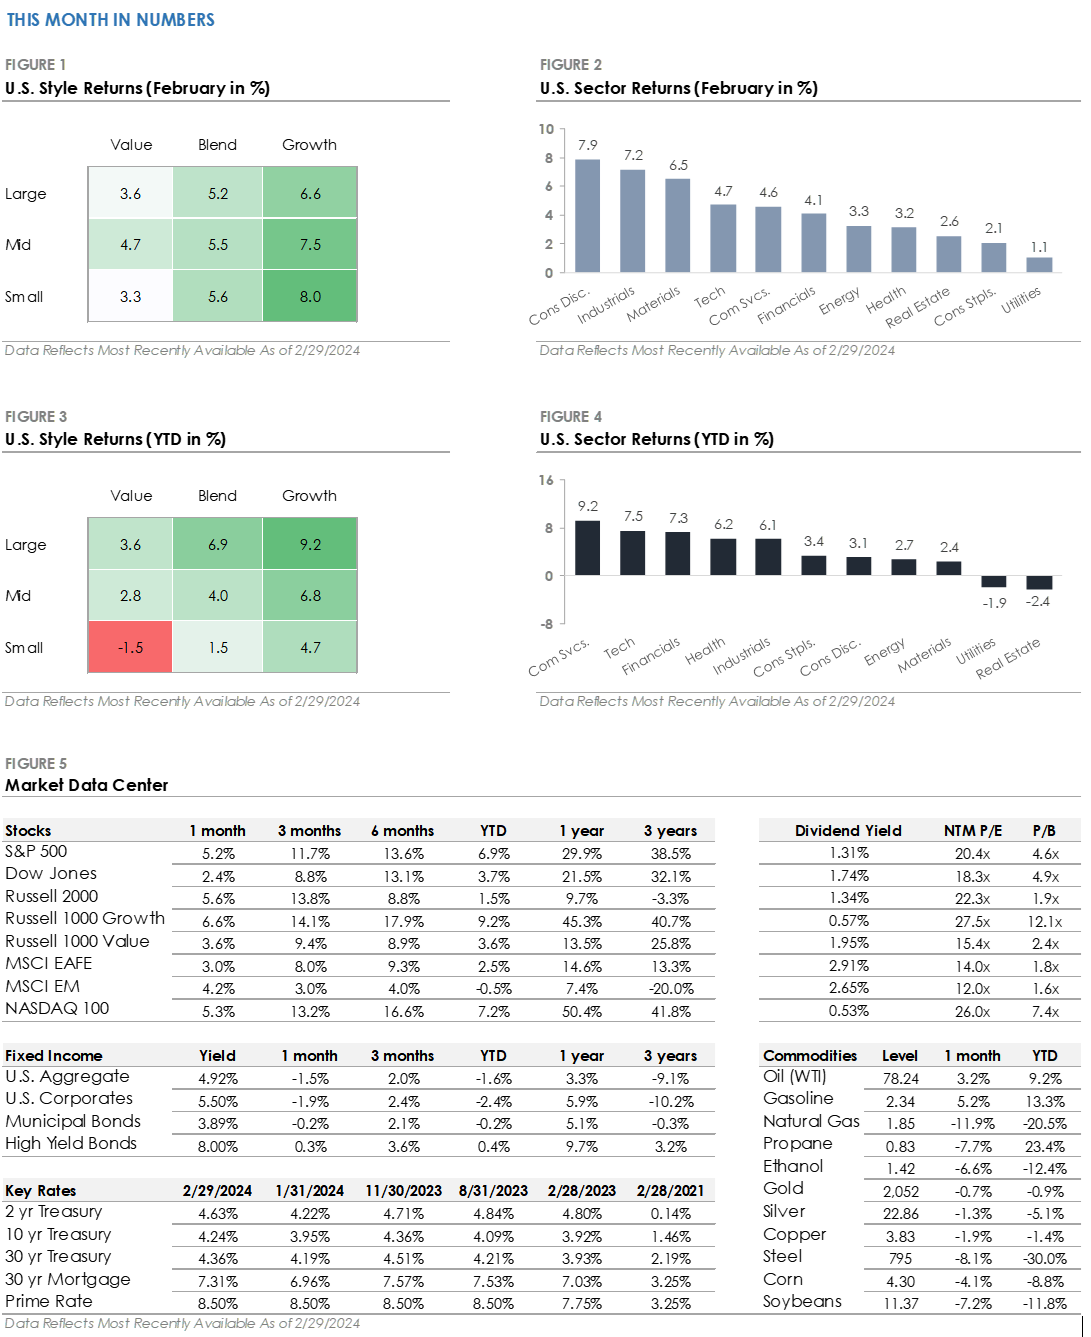
  • The S&P 500 Index gained +5.2%, underperforming the Russell 2000 Index’s +5.6% return. All eleven S&P 500 sectors traded higher, with cyclical sectors outperforming.
  • Corporate investment-grade bonds produced a -1.9% total return as Treasury yields rose, while corporate high-yield bonds produced a +0.3% total return.
  • International stocks underperformed U.S. stocks. The MSCI EAFE Index of developed market stocks returned +3.0%, while the MSCI Emerging Market Index gained +4.2%.


Stocks Trade Higher for a Fourth Consecutive Month, While Bonds Trade Lower

Stocks traded higher in February, with the rally broadening after large cap stocks accounted for most of January’s gains. The S&P 500 traded above 5,000 for the first time, setting a new all-time high, and has now returned +21.5% since the start of November. The Dow Jones Industrial Average set a new closing high in February, and the Russell 2000 Index of small cap stocks outperformed the S&P 500 after trailing by -5.5% last month. The Consumer Discretionary, Industrial, and Material sectors outperformed the S&P 500, while the Utility, Consumer Staple, and Real Estate sectors underperformed.

In the credit market, bonds traded lower for a second consecutive month as two themes caused rates to rise. First, the Federal Reserve told investors it wants more confirmation that inflation will return to its 2% target. This statement effectively pushed back the timing of the first interest rate cut. Second, multiple inflation reports were hotter than expected, hinting at sticky inflation. This year’s bond sell-off suggests the market got ahead of itself by forecasting too many rate cuts. Investors now expect three rate cuts this year, a decrease from the forecast for six rate cuts at the start of the year.

Commodity Price Index Trades Near a 2-Year Low, But Energy Prices Are Rising

The Bloomberg Commodity Index, which tracks a broad group of commodities, currently trades at its lowest level since December 2021. It’s been a volatile two years. Commodity prices spiked in early 2022 after Russia’s invasion of Ukraine disrupted the energy, metal, and agriculture markets. The sharp rise in commodity prices sent inflation soaring above 9% in June 2022, the highest level in 40 years. Since peaking in mid-2022, commodity prices and inflation have both trended lower. The consumer price index rose by 3.1% year-over-year in January 2024, the slowest since March 2021.

Investors and the Federal Reserve are debating the risk of a second inflation wave. The price declines across commodity markets helped ease inflation pressures, but there are questions about whether the trend can continue. The price of crude oil has risen by +9.2% year-to-date and currently trades at a 3.5-month high, while gas prices have risen by +13.3% this year. With the summer driving season fast approaching, there is concern that gasoline prices could continue to rise. Investors will be watching other commodity markets to see if prices start to rise, as that could delay the Fed’s plan to cut rates.
Annualized Return: The rate at which an investment grows each year over the period to arrive at the final valuation.

Bear Market: A decline of at least 20% from the market’s high point to its low.

Beta: A measure of how an individual asset moves when the overall stock market increases or decreases.

Correlation: A measure of the extent to which two variables are related.

Dividend Yield: The dividend yield or dividend-price ratio of a share is the dividend per share, divided by the price per share. It is also a company’s total annual dividend payments divided by its market capitalization, assuming the number of shares is constant.

Developed Markets: A country that is most developed in terms of its economy and capital markets. The country must be high income, but this also includes openness to foreign ownership, ease of capital movement, and efficiency of market institutions.

Emerging Markets: A country that has some characteristics of a developed market but does not fully meet its standards. This includes markets that may become developed markets in the future or were in the past.

Growth Factor Stocks: Growth stocks are companies expected to grow sales and earnings at a faster rate than the market average.

Large Cap Stocks: Shares of publicly traded corporations with a market capitalization of $10 billion or more.

LTM: An acronym for “Last Twelve Months” or the past one year.

NTM: An acronym for “Next Twelve Months” or the next one year.

Price Return: The rate of return on an investment portfolio, where the return measure takes into account only the capital appreciation of the portfolio, not including income generated in the form of interest or dividends.

Total Return: Return on a portfolio of investments including capital appreciation and income received on the portfolio.

Small Cap Stocks: Small-cap stocks are shares of companies with a market capitalization of less than $2 billion.

Standard Deviation: In statistics, the standard deviation is a measure of the amount of variation or dispersion of a set of values. A low standard deviation indicates the values tend to be close to the historical average of the data set, while a high standard deviation indicates the current value is outside of the historical average range.

Value Factor Stocks: Stocks that are inexpensive relative to the broad market based on measures of fundamental value (e.g., price to earnings or price to book).

Disclosures and legal notice

DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss and is not suitable for every investor. The valuation of futures, stocks and options may fluctuate, and, as a result, clients may lose more than their original investment. The impact of seasonal and geopolitical events is already factored into market prices. The highly leveraged nature of futures trading means that small market movements will have a great impact on your trading account and this can work against you, leading to large losses or can work for you, leading to large gains.

  • If the market moves against you, you may sustain a total loss greater than the amount you deposited into your account. You are responsible for all the risks and financial resources you use and for the chosen trading system. You should not engage in trading unless you fully understand the nature of the transactions you are entering into and the extent of your exposure to loss. If you do not fully understand these risks you must seek independent advice from your financial advisor. All trading strategies are used at your own risk.
  • Any content on T2 Markets Research should not be relied upon as advice or construed as providing recommendations of any kind. It is your responsibility to confirm and decide which trades to make. Trade only with risk capital; that is, trade with money that, if lost, will not adversely impact your lifestyle and your ability to meet your financial obligations. Past results are no indication of future performance. In no event should the content of this correspondence be construed as an express or implied promise or guarantee.
  • T2 Markets Research is not responsible for any losses incurred as a result of using any of our trading strategies. Loss-limiting strategies such as stop loss orders may not be effective because market conditions or technological issues may make it impossible to execute such orders. Likewise, strategies using combinations of options and/or futures positions such as “spread” or “straddle” trades may be just as risky as simple long and short positions. Information provided in this correspondence is intended solely for informational purposes and is obtained from sources believed to be reliable. Information is in no way guaranteed. No guarantee of any kind is implied or possible where projections of future conditions are attempted.

Disclaimer: None of the content published on T2 Markets Research constitutes a recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. None of the information providers or their affiliates will advise you personally concerning the nature, potential, value or suitability of any particular security, portfolio of securities, transaction, investment strategy or other matter.

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Keep reading

More from the research library

Packed economic and earnings calendar

U.S. equities delivered a mixed performance this week as investors navigated a sharp decline in Treasury yields, escalating geopolitical risk, and growing concerns about the sustainability of the
AI investment boom. Beneath the headline indices, the divergence between technology stocks and the broader market became increasingly pronounced as investors reassessed the valuations of companies at the center of the AI trade.

Read more →

Hotter-than-expected inflation data pressures markets

U.S. equities came under renewed pressure this week as hotter-than-expected inflation data forced investors to reassess both the interest rate outlook and the sustainability of the AI investment boom. The September CPI report showed headline inflation rising 0.6% for the month and 3.7% year-over-year, while core CPI increased 0.3% for the month and 2.6% for the year—this reading comes in above both the Fed’s stated 2.0% target and the high end of economist expectations.

Read more →

Credit-market stability and earnings quality

U.S. equity markets overall continued to rise, with both the S&P 500 and Nasdaq notching fresh all-time highs. The beleaguered Russell small cap index, however, continued to underperform. European markets were down modestly while Asian markets advanced. Treasury yields surged to fresh highs on Wednesday before cooling by the week’s end as rates and borrowing costs remained a major focus.

Read more →

Free newsletter

Market Research & Analysis

Get our latest reports and commentary delivered to your inbox.

Inside a recent report

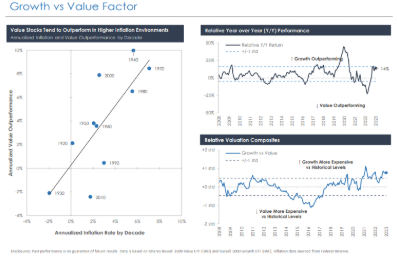
Growth vs Value Factor chart

Growth vs Value Factor — one of the charts from our research.